
Round-the-world travel insurance: how much it costs in 2026
When planning a round-the-world trip, you shouldn’t overlook the insurance budget.
Let’s see why insurance is a must-have, with a comparison of the different options available.
Why get insured on a round-the-world trip?
There are countless insurance policies that offer to cover your expenses in case of flight delays, lost luggage, theft, or a broken phone, …
While these events are unfortunate, they’re manageable. I tend not to pay for insurance for that.
What you need to plan for is the worst-case scenario: you crash a scooter in Bali and need emergency surgery or a medical evacuation.
In many cases, that’ll run you tens of thousands of euros. And in many countries, they’ll wait until you’ve paid before they hook up your first IV.
It’s never fun to think about this while preparing for a round-the-world trip, but it doesn’t only happen to others.
Proof: it happened to me in Vietnam.
Am I covered by French health insurance?
You might still be covered by French health insurance during your round-the-world trip. For example, if you resign from your job, you remain affiliated for one year.
That raises the legitimate question: is French health insurance enough for your trip?
As long as you stay within the European Union, the answer is yes. Remember to get your European Health Insurance Card (EHIC) before you leave.
If you leave the European Union, the answer is no.
Here’s what you can read on the French Health Insurance website.
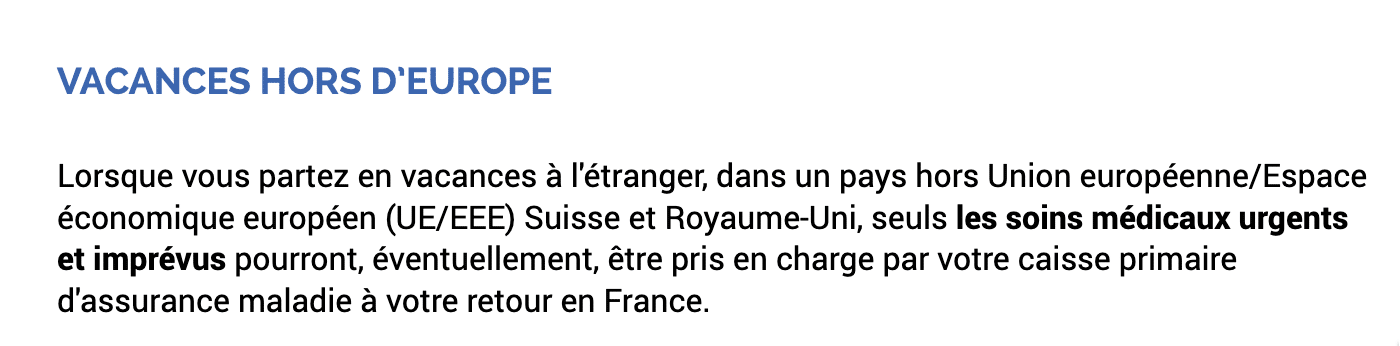
The word “possibly” is important. In an emergency requiring hospitalization or medical evacuation, your health insurance won’t be of any help. You’ll have to fend for yourself, front the costs, and hope for possiblya reimbursement once everything is over.
Am I covered by my bank card?
Many bank cards offer travel insurance covering hospitalization and medical evacuation costs.
However, as far as I know, they all limit coverage to the first 90 days of travel.
So a specific additional insurance policy is essential.
That said, to cut costs, you might consider taking out the specific policy only after the first 90 days of travel.
In that case, double-check the general terms and conditions of the insurance policies:
- Some card insurances only cover you if you paid for your trip with that card
- Some specific insurance policies won’t cover you if your trip has already started
Price simulations for round-the-world insurance
Here’s a table comparing prices from various specialized travel insurance providers.
We’ll use the following assumptions:
- The trip lasts 12 months
- We’re insuring a couple aged 25 (so the price shown is for two people)
We’ll request two quotes: one excluding the USA/Canada (which significantly bump up the bill) and one including 2 months of travel in the USA and Canada.
These simulations were run on January 14, 2023
| Insurance | Price excluding USA/Canada | Price including USA/Canada |
|---|---|---|
| Chapka (Cap Aventure) | 1 181 € | 1 341 € |
| AVI (Marco Polo) | 1 503 € | 1 974 € |
| ACS (Globe Partner) | 864 € | 864 € |
| ACS (Globe Traveller) | 1 200 € | 2 112 € |
| AVA (Plan Santé AVAnture) | 1 128 € | Date-to-date option |
| Yupwego | 1 048 € | 1 209 € |
| Europ Assistance (Evasio Grand Voyage) | 1 384 € | 1 384 € |
| April International (Emergency plan) | 909 € | 1 677 € |
| Heymondo | 1 242 € | 1 614 € |
| Allianz Travel | 1 035 € | 1 184 € |
| Mondial Care | 1 598 € | 2 598 € |
| American Express | 1 548 € | 1 906 € |
Rates are one thing, but let’s now look at the amount of the most important coverages.
Repatriation cost coverage
In the event of a serious accident requiring repatriation, the costs can quickly add up. The insurance will need to charter a medical plane with staff to take care of you. If you’re on the other side of the world, that plane will be too small to make the trip in one go; you’ll need one or more stopovers…
Suffice it to say this is important, and the magic word will be “actual costs,” meaning the insurance will cover the full amount, without limit, no cap.
You don’t want to be told that the plane costs more than the cap, and that you have to figure it out on your own…
| Insurance | Repatriation coverage |
|---|---|
| Chapka (Cap Aventure) | Actual costs |
| AVI (Marco Polo) | Actual costs |
| ACS | Actual costs |
| AVA (Plan Santé AVAnture) | Actual costs |
| Yupwego | Actual costs |
| Europ Assistance (Evasio Grand Voyage) | Actual costs |
| April International (Emergency plan) | Actual costs |
| Allianz Travel | Actual costs |
| Mondial Care | Actual costs |
| American Express | Actual costs |
| Heymondo | Actual costs |
Fortunately, they all cover actual costs. Never choose an insurance that doesn’t!
Serious medical expenses
This is the second most important line to check: the reimbursement cap for severe cases requiring surgery or hospitalization. The cap should be as high as possible.
| Insurance | Cap for USA/Canada | Cap for Europe | Cap for rest of the world |
|---|---|---|---|
| Chapka (Cap Aventure) | €1,000,000 (€35 deductible) | 200 000 € | 200 000 € |
| AVI (Marco Polo) | 300 000 € | 100 000 € | 300 000 € |
| ACS | 300 000 € | 300 000 € | 300 000 € |
| AVA (Plan Santé AVAnture) | 1 000 000 € | 300 000 € | 300 000 € |
| Yupwego | 1 000 000 € | 80 000 € | 300 000 € |
| Europ Assistance (Evasio Grand Voyage) | 300 000 € | 150 000 € | 300 000 € |
| April International (Emergency plan) | Actual costs | Actual costs | Actual costs |
| Allianz Travel | €300,000 (USA/Canada/Australia) | 200 000 € | 200 000 € |
| Mondial Care | €700,000 (€50 deductible) | €300,000 (€50 deductible) | €300,000 (€50 deductible) |
| American Express | 150 000 € | 75 000 € | 75 000 € |
| Heymondo | 300 000 € | 300 000 € | 300 000 € |
Given the cost of medical care in North America, I’d feel more comfortable with a cap close to a million euros. For the rest of the world, €300,000 seems fine. Below €200,000, it’s probably a bit tight.
Liability coverage cap
Important point: liability. It comes in two types:
- Property damage liability: if you accidentally set your accommodation on fire, for example.
- Bodily injury liability: if you accidentally injure or kill someone, e.g., in a car accident.
| Insurance | Property damage liability cap | Bodily injury liability cap |
|---|---|---|
| Chapka (Cap Aventure) | 450 000 € | €4,500,000 (limited to €1,500,000 in USA/Canada) |
| AVI (Marco Polo) | 750 000 € | 750 000 € |
| ACS | 450 000 € | 4 500 000 € |
| AVA (Plan Santé AVAnture) | 450 000 € | 4 500 000 € |
| Yupwego | 450 000 € | 4 500 000 € |
| Europ Assistance (Evasio Grand Voyage) | 4 000 000 € | 4 000 000 € |
| April International (Emergency plan) | 450 000 € | 4 500 000 € |
| Allianz Travel | 450 000 € | 4 500 000 € |
| Mondial Care | €2,000,000 (limited to €500,000 in USA/Canada) | 500 000 € |
| American Express | 4 500 000 € | 4 500 000 € |
| Heymondo | 100 000 € | 100 000 € |
Caps below a million euros for the USA seem too low to me. You all have in mind staggering amounts from high-profile lawsuits. These are extreme cases, but if insurance doesn’t cover you the day it happens…
Reimbursement for medical consultations
We’re talking about more routine medical consultations, “non-urgent”: if you’re sick and need medication. The amounts at stake are much smaller than the points above. If the insurance covers them, it’s a real bonus.
| Insurance | Reimbursement for consultations | Reimbursement for medications |
|---|---|---|
| Chapka (Cap Aventure) | Not specified | Not specified |
| AVI (Marco Polo) | €100,000 in Europe, €300,000 in the rest of the world | Same |
| ACS | Actual costs | Actual costs |
| AVA (Plan Santé AVAnture) | Actual costs | Actual costs |
| Yupwego | Not specified | Not specified |
| Europ Assistance (Evasio Grand Voyage) | Not specified | Not specified |
| April International (Emergency plan) | Actual costs (with a maximum of €750 per year for the Emergency plan, unlimited for the Comfort plan) | Same |
| Allianz Travel | Not specified | Not specified |
| Mondial Care | Not specified | Not specified |
| American Express | Not specified | Not specified |
| Heymondo | 300 000 € | 300 000 € |
Even when reading the fine print, the distinction between caps for urgent and non-urgent cases is not always very clear. Don’t hesitate to ask for clarification before subscribing.
Dental care reimbursement
| Insurance | Emergency dental care | Dental care following an accident |
|---|---|---|
| Chapka (Cap Aventure) | €600 / year | €440 / tooth with a maximum of €1,300 per claim. |
| AVI (Marco Polo) | 150 € | €500 / tooth |
| ACS | 300 € | 600 € |
| AVA (Plan Santé AVAnture) | 300 € | 300 000 € |
| Yupwego | 300 € | / |
| Europ Assistance (Evasio Grand Voyage) | 160 € | / |
| April International (Emergency plan) | €400 / year | €800 / year |
| Allianz Travel | 1 000 € | / |
| Mondial Care | €200 / claim | / |
| American Express | 250 € | / |
| Heymondo | 300 € | / |
Extreme sports / high altitude
Last but not least, extreme sports and high altitude.
I haven’t done the research for all insurance policies because you really have to read between the lines, but know that there can be coverage exclusions:
- For what insurers consider “extreme” sports: off-piste skiing, skydiving, scuba diving
- For high altitude: insurers generally consider high altitude as “above 4,000 meters in altitude”. An altitude that is very easy to reach in some parts of the world
AVA offers a SPORT+ option at €10 per month that covers accidents resulting from air sports and increases the search and rescue cost cap to €25,000 instead of €5,000, as well as the practice of risky sports.
If you’re planning this type of activity (a trek in Nepal, for example), you should consider taking out specific additional insurance.